No-Cost EMI Isn’t Really Free: The Hidden GST Charges That Make Your Phone More Expensive
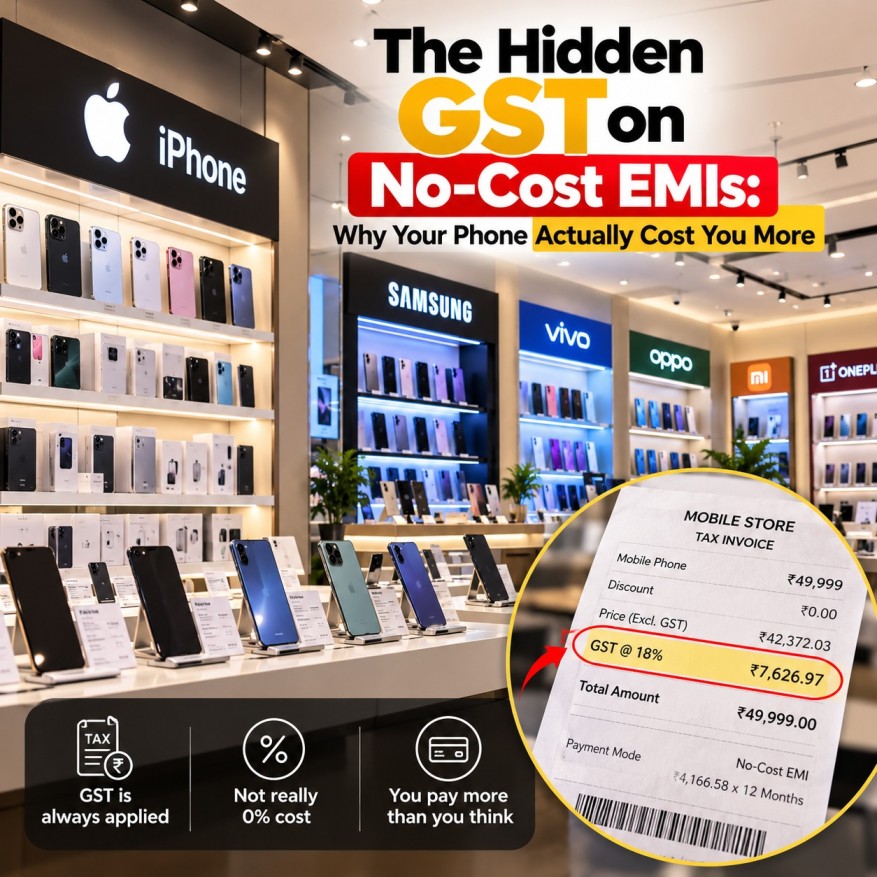
Buying a new smartphone has become easier with online shopping, festive sales, and flexible payment options. One offer that attracts customers almost instantly is No-Cost EMI. It promises the convenience of paying for an expensive phone in monthly instalments without paying additional interest out of pocket.
However, the advertised monthly payment does not always represent the complete cost of your purchase. Depending on the financing arrangement, customers may encounter processing fees, GST on applicable charges, interest-related costs, and discounts that are unavailable when choosing EMI.
This raises an important question: Is No-Cost EMI really free, or are you paying more than you realise?
Understanding the hidden GST on No-Cost EMI can help smartphone buyers compare payment options, identify additional expenses, and make smarter purchasing decisions.
What Is No-Cost EMI?
No-Cost EMI is a payment facility that allows customers to purchase products, such as smartphones, laptops, and home appliances, through fixed monthly instalments. Instead of paying the entire amount immediately, the buyer repays the financed amount over an agreed period.
In many offers, the bank or finance provider charges interest, while the retailer or manufacturer provides a discount or interest subsidy to offset that cost. As a result, the customer may see instalments that add up to approximately the advertised purchase price.
However, the exact arrangement depends on the lender, merchant, product, and offer terms.
For example, a smartphone priced at ₹60,000 might be available through a six-month No-Cost EMI plan with instalments of ₹10,000. At first glance, the total appears to be exactly ₹60,000. Yet additional fees, applicable taxes, or a foregone upfront discount could increase the amount the customer effectively pays.
That is why checking the complete cost is more important than focusing only on the monthly instalment.
How Does GST Affect No-Cost EMI?
Goods and Services Tax (GST) may increase the cost of an EMI purchase when it applies to particular financing charges or services.
A key distinction is that GST does not automatically apply to every component of every No-Cost EMI transaction in the same way. The treatment depends on the nature of the charge and the financing arrangement.
Here are the main areas buyers should understand.
1. GST on EMI Processing Fees
Some banks and financial institutions charge a processing or EMI conversion fee when a purchase is converted into instalments. This fee covers the administrative or service-related aspects of arranging the financing.
Where the processing fee is taxable, GST is charged in addition to the fee.
Consider an illustrative example:
- EMI processing fee: ₹299
- GST at an assumed rate of 18%: ₹53.82
- Total processing charge: ₹352.82
The customer would pay ₹352.82 in processing-related charges rather than just ₹299.
The actual fee, applicable GST rate, and any promotional waiver depend on the lender's terms. Therefore, buyers should review the fee schedule before confirming the transaction.
2. GST on Interest-Related Charges
Another point that creates confusion is GST associated with interest on EMI transactions.
The GST treatment of interest depends on the type of financial service involved. Under the general GST framework, interest on loans and advances is generally exempt, subject to specified exceptions. Credit-card-related interest has different treatment, while separate service charges may remain taxable.
Consequently, customers should not assume that every No-Cost EMI plan attracts GST on the entire interest amount. The applicable terms and the nature of the financing arrangement must be checked.
If a lender charges interest, the customer should examine whether it is offset by a merchant subsidy or discount and whether any additional tax or fee appears in the repayment schedule or statement.
This distinction helps buyers understand which costs are genuine tax charges and which arise from the financing structure itself.
The Hidden Cost of No-Cost EMI: Discounts You Might Miss
GST is only one part of the overall picture. In some cases, the most significant expense associated with No-Cost EMI is the discount a customer gives up by choosing instalments.
Retailers may offer different prices or promotional benefits depending on the payment method. An instant bank discount, cashback offer, or upfront-payment benefit may not be available with a particular EMI plan.
For example, imagine the following offer:
|
Purchase Detail |
Amount |
|---|---|
|
Smartphone Price |
₹60,000 |
|
Discount on Upfront Payment |
₹3,000 |
|
Effective Upfront Purchase Price |
₹57,000 |
|
Total Scheduled No-Cost EMI Payments |
₹60,000 |
In this hypothetical example, choosing No-Cost EMI means paying ₹3,000 more than the discounted upfront option, before considering any additional fees or applicable taxes.
The EMI option may still suit someone who needs to spread payments over several months. However, it is not necessarily the cheapest option.
The important comparison is between the final cost of EMI and the best available upfront price, not simply between the advertised interest rate and zero.
Why Your Smartphone May Cost More Than Expected
Several factors can affect the final amount paid for a phone purchased through No-Cost EMI.
Processing and Conversion Charges
A one-time processing or conversion fee can increase the cost of financing. Even a relatively small fee becomes relevant when the product is advertised as having no additional cost.
GST on Taxable Fees
GST may apply to processing, administrative, or other taxable service charges. These amounts can appear separately in the lender's documentation or account statement.
Missing Bank Discounts or Cashback
Some promotional benefits are conditional on the payment method. If an upfront discount is unavailable with EMI, the lost savings should be included when comparing offers.
Credit Card and Loan Conditions
Credit-card EMI and consumer-durable loans may follow different pricing structures and terms. Customers should check the interest arrangement, repayment schedule, fees, andconditions for